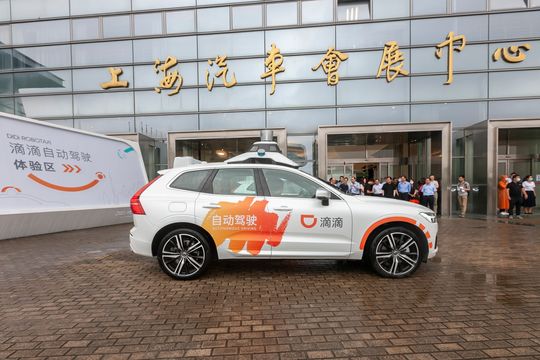
China has followed through on its promise to clamp down on stricter rules for its companies listed overseas or selling shares abroad. The American depositary shares of Didi Global Inc., a China-based ride-hailing company, opened trading on June 30, 2021, and the day before that, Didi raised the largest IPO haul for a Chinese company during its initial public offering since Alibaba Group Holding Ltd. This performance was a sign of American investors hooked by Didi’s potential for high growth despite risks. Wall Street has historically provided a bridge for American investors to profit off of China’s rising economy in spite of drastic political disagreements between the U.S. and Chinese governments.
However, it seems the tension of opposing political divisions has finally snapped, with Chinese and American companies suffering from being a middleman. Beijing’s vision of technology, data protection, and security differs irrevocably from Washington. China has stepped onto Wall Street with Didi, giving the company a series of regulatory actions since its stock debut and even recommending delaying the initial public offering, citing concerns that the requirements to file as a U.S.-listed company could make Didi an accomplice in giving the U.S. Chinese data. These explicit regulations could deter other Chinese companies from planning a U.S.-listed IPO anytime soon. American investors are left uncertain in formerly profitable deals like fast-growing Chinese startups. Fund managers who bought Didi shares can only watch as the stock dropped in value.
Chinese President Xi Jinping is advancing his message that the nation should be put ahead of business. On July 6, 2021, new regulations “on data security, cross-border data flow and other confidential information management” were released through state-run Xinhua News Agency. The needs for increasing restrictions were cited to be necessary in what Chinese officials called an environment of increasing lawlessness in capital markets. The government proposed a revision of stock offering rules on exchanges occurring abroad, greater domestic regulatory body liability, and better interagency coordination. The government has also been attempting to shut down a legal loophole that has allowed Chinese companies to walk around the regulatory scrutiny and rigorous IPO vetting that domestic listing entails by registering interest entity structures in offshore tax havens out of China’s legal jurisdiction.
A crucial tool in President Xi’s belt to regulate U.S.-listed Chinese companies is the Cyberspace Administration of China. According to Victor Shih, a University of California, San Diego, professor of political economy, “the cyber regulator has become the new securities regulator. Investors and companies will find it much harder to manage the listing process.” This cyberspace agency is a physical embodiment of the Chinese Communist Party’s distrust of markets and private entrepreneurs. One of China’s biggest private firms, Ant Group, had its initial public offering blocked because Xi believed profits were put above the state’s goal of monitoring financial risk. Putting an emphasis on state rather than money could slow the Chinese economy by whittling down the innovation and competition typically associated with a freer market. Policies that allowed for historic economic successes like Alibaba Group Holding Ltd. could be left only in history books speaking of past eras.
The contrast in economic motivation between the U.S., mainly driven by private consumption, and China, mainly driven by state agendas, forces overseas companies to attempt to reconcile the two bodies of regulation, despite oftentimes directly contradicting laws between the two countries. At the same time as the Chinese cyberspace administration makes selling overseas shares more difficult, U.S. lawmakers like Senator Marco Rubio (R., Fla.) are calling on the U.S. to prevent Chinese firms from going public in the U.S. if they do not fulfill U.S.-style audit requirements. Some Chinese companies have had to deny the U.S. Securities and Exchange Commission’s request for company audits because China’s laws do not allow them to hand over audits to the U.S. In following domestic law, Chinese companies risk being delisted from U.S. markets for non-compliance with U.S. law. Chinese companies are now looking at a problematic future of constantly tiptoeing a careful line between U.S. and Chinese demands.

